Financial & Tax Consulting

M&A advisory in Thailand

Merger and acquisition (M&A) advisory for founders, CFOs, and investors in Thailand. When a private equity (PE) fund shows interest or a letter of intent (LOI) arrives, you want to close at the right price, without a late due diligence finding or a tax structuring mistake eating into your proceeds.

Get a quote, typically returned in 1 business day
No commitment · Written reply within 1 business day · Published prices

FAP

Registered CPAs

DFK

International Network

200+

Clients Served

1 day

Reply Time

What You Get

M&A support from first look to integration

  • Financial and tax due diligence

    We review three to five years of financials for hidden liabilities, tax exposures, and quality of earnings. One team covers both finance and tax, so nothing falls between two firms.

  • Defensible valuation

    Discounted cash flow (DCF), comparable companies, and precedent transactions give you a valuation range you can negotiate from, not a single number to defend.

  • Tax-efficient deal structure

    Share purchase, asset transfer, or a Section 74 amalgamation or business transfer, each modeled with its full Thai tax outcome. The wrong structure can cost 5–15% of deal value in unplanned tax.

  • Post-closing integration

    Financial consolidation, purchase accounting, and tax structure implementation, ready so integration starts on day one.

2015

Founded in Bangkok

200+

Active SME clients

CFO

Led advisory

How It Works

Our Process

A clear, structured approach from start to finish.

  1. Step 1:Transaction strategy and scoping

    We define the mandate (buy-side or sell-side), the workstreams, and any obligations to the Office of Trade Competition Commission (OTCC) or the Stock Exchange of Thailand (SET). We check the OTCC timeline here, because finding it mid-process is a common cause of delayed closings.

  2. Step 2:Preliminary assessment

    A first financial and operational review of the target, with a first pass at normalized EBITDA. Decision gate: go to full due diligence or stop.

  3. Step 3:Detailed financial and tax due diligence

    A full review of 3–5 years of financial statements, tax returns (corporate income tax, VAT, withholding tax, and transfer pricing), related-party transactions, and contingent liabilities, in one working file.

  4. Step 4:Valuation and deal pricing

    A valuation range built on several methods, delivered before negotiation starts, with the assumptions behind each end of the range.

  5. Step 5:Deal structure and negotiation

    Share purchase, asset purchase, or a Section 74 transfer, chosen on Thai tax outcomes modeled for both parties. The key trade-offs are put in writing before the structure is locked.

  6. Step 6:Closing and integration

    We coordinate closing documents, post-closing accounting entries, and tax structure implementation, then support the integration of the finance function.

Transparent Pricing

M&A Advisory: Bespoke Engagement Structure

M&A fees combine a fixed retainer with a success-fee component. Structure scopes by deal value, target complexity, and cross-border elements.

About our pricing:

Standard: smaller asset purchases

Single-target Thai entity, THB 10–50M deal value, clean books, single-jurisdiction shareholders, no regulatory carve-outs. Scoping, financial / tax DD, valuation, deal coordination through closing.

Govt / 3rd-party fees
DBD registration (variable) + stamp duty 0.1% of share value + capital gains / CIT on disposal
Plizz service fee
Bespoke · retainer + success fee

Reason for quote:Why: retainer + success fee % of deal value: deal-dependent structure

Most common

Mid-market

THB 100–500M deal value, financial + tax + light legal due diligence, OTCC notification considerations, single-jurisdiction with possible foreign component.

Govt / 3rd-party fees
DBD + newspaper publication (~500–1,500) + stamp duty 0.1% + capital gains / CIT
Plizz service fee
Bespoke · retainer + success fee

Reason for quote:Why: retainer + success fee scales with deal value, DD scope, and cross-border elements

Complex: cross-border / regulated

Cross-border deal, multi-target / portfolio acquisition, regulated-industry target (financial services, healthcare, telecoms), OTCC pre-merger approval, Section 74 tax-neutral structuring, multi-jurisdiction tax planning.

Govt / 3rd-party fees
DBD + newspaper + stamp duty + capital gains tax + multi-jurisdiction tax
Plizz service fee
Bespoke · retainer + success fee

Reason for quote:Why: cross-border + regulated industry + multi-jurisdiction tax = highest retainer + success-fee tier

Optional Add-Ons

Part-time CFO support pre-/post-deal

Get a quote · 1 business day

Reason for quote:Why: engagement intensity scopes with deal stage and post-merger integration depth

Especially valuable for sell-side preparation and post-merger integration. See Part-time CFO.

Tax advisory on transaction structure

Get a quote · 1 business day

Reason for quote:Why: project scope depends on jurisdictions and structuring options

Critical for tax-efficient deal structuring. See Tax Advisory.

Legal due diligence

Quoted by corporate-law firm partner · Plizz coordinates

Reason for quote:Why: coordinated with Plizz Group network; partner fee scales with deal complexity

Coordinated with Plizz Group's network of corporate-law firms.

Annual statutory audit (post-deal)

Quoted by CPA partner · Plizz coordinates

Reason for quote:Why: CPA fee scales with post-deal revenue + transaction volume + subsidiaries

Often required by acquirers post-closing. See Annual Audit Compliance.

Pricing Notes

  • All Plizz fees exclude 7% VAT.
  • Fee structure typically combines a fixed retainer with a success-fee component.
  • DFK International network: Plizz leverages its DFK membership for cross-border transactions across 85+ countries, useful for buy-side targets in or sell-side acquirers from outside Thailand.
  • Government / 3rd-party fees (DBD, stamp duty 0.1%, capital gains / CIT on disposal gain) are pass-through; planned for in advisory.

Build your quote: Plizz confirms it within 1 business day

Get a quote

Estimate excludes 7% VAT and government fees. Plizz confirms your final quote within 1 business day.

Thai regulatory context

Three Thai rules that can stop a deal late

Three Thailand-specific rules shape most M&A outcomes. Each one can delay or kill a deal if you find it late.

Trade Competition Act B.E. 2560: approval before closing

A deal needs pre-merger approval from the Office of Trade Competition Commission (OTCC) when the combined business would hold a dominant position: generally >50% market share, or a top three with >75% combined share, together with revenue above THB 1 billion. The filing is suspensory: the deal cannot close until the OTCC clears it, and the OTCC has 90 days (extendable by 15) to decide. Other deals above the revenue threshold must notify the OTCC within 7 days of closing. Finding this out mid-process is a common cause of delayed closings in Thailand.

Section 74 tax-neutral treatment: all or nothing

Revenue Code Section 74 allows tax-neutral treatment of qualifying amalgamations and business transfers, deferring a gain that would otherwise be taxed on transfer. Qualifying usually requires consideration made up mainly of shares (cash consideration generally disqualifies), continuity of the business after closing, and the procedural steps of the Civil and Commercial Code (registrar filings and creditor notices under CCC Sections 1238–1273). Miss any one condition and the full gain is taxed in the year of transfer. Goodwill is also generally not tax-deductible in Thailand, so the purchase price allocation between goodwill and identifiable intangibles sets the post-deal effective tax rate for years.

Tax losses, Section 65 Ter, and cross-border rules

Under Section 65 Tri (12), net operating losses carry forward for up to 5 years. In a share purchase the losses survive, because the legal entity continues. In an asset purchase they do not. For a target with large accumulated losses, decide the structure before signing. Section 65 Ter disallows expenses such as fines, personal expenses, and payments without proper evidence, items that often surface in due diligence and change the price. In cross-border deals, Bank of Thailand (BOT) foreign exchange rules govern how proceeds are moved abroad, and the Securities and Exchange Act B.E. 2535 adds connected transaction disclosures for SET-listed parties.

What happens when the SPA misses pre-closing tax

If the share purchase agreement (SPA) does not carve out tax liabilities from before closing, the buyer takes them on, and the price or the escrow is adjusted to match. Founder net proceeds can fall 5–15%. We see this in deals where financial and tax due diligence were rushed, split between firms, or left too late. Plizz runs both in one working file, so nothing the financial review finds is missed by the tax review.

Provider comparison

Plizz compared with the alternatives

Most buyers and sellers compare advisors before they engage one. Here is how the main options differ.

DimensionPlizzBig 4 transaction servicesInvestment bankDo it yourself (founder-led)
Senior attentionPartner-led; the founders bring hands-on CFO and transaction experiencePartner signs; managers and seniors do most of the workBanker leads; process-heavyFounder manages; issues often surface after signing
Fee structureSized for mid-market deals; fixed retainer plus success feePremium pricing built for listed and large-cap dealsSuccess fee on deal value; costly for mid-market dealsLowest upfront; highest risk-adjusted cost
Thai tax depthFinancial and tax due diligence in one team; Revenue Code, OTCC, BOT foreign exchange, and SEC rulesSeparate tax and financial teams; gaps between them are possibleUsually outsources tax due diligenceNo structured tax review
Cross-borderDFK International member firms in 85+ countries; Narai Partners (IR Global) for legalGlobal network by designRegional desk coverageNo network
Best forMid-market deals of THB 10M–1B+, growth companies, and founder exitsListed-company deals above THB 1BSell-side processes run as auctionsDeals below THB 10M between parties who know each other

Who this is for

Who needs M&A advisory?

M&A advisory is for mid-market buyers, sellers, and investors preparing or running a deal whose financial and tax questions are more than an internal team can handle alone.

  • Private equity and venture capital funds running buy-and-build strategies in Thailand

    Buy-side financial and tax due diligence across several targets, normalized EBITDA, quality of earnings analysis, and management incentive structuring. The DFK International network helps when the fund holds assets in several countries.

  • Founders or shareholders preparing for a full or partial exit

    Sell-side preparation, valuation defense, a vendor due diligence pack, tax-efficient structuring of the gain on sale (personal income tax for individual sellers, 20% corporate income tax for corporate sellers), and earn-out negotiation. Sell-side preparation should start well before the target closing date.

  • Strategic buyers: multinational groups making add-on acquisitions in Thailand

    Local financial and tax due diligence, OTCC pre-merger filing assessment under the Trade Competition Act B.E. 2560, Section 74 structuring review, analysis of whether BOI privileges survive the deal, and integration with group accounting and tax systems.

  • Family-office acquirers and distressed-asset buyers

    Financial due diligence on targets with incomplete books, normalized earnings, and an acquisition vehicle structured to keep post-deal tax costs low.

  • Listed-company finance teams subject to SET disclosure

    Connected transaction review, fairness opinion support, and analysis of disclosure obligations under the Securities and Exchange Act B.E. 2535 (1992).

This is not the right engagement if the deal is below about THB 10M between parties who know each other (your accountant and a corporate lawyer usually cover it), if the "M&A" is an internal group restructuring with no third party (we scope that as a restructuring engagement), or if you need someone to find acquisition targets (that is a broker’s mandate, not an advisor’s).

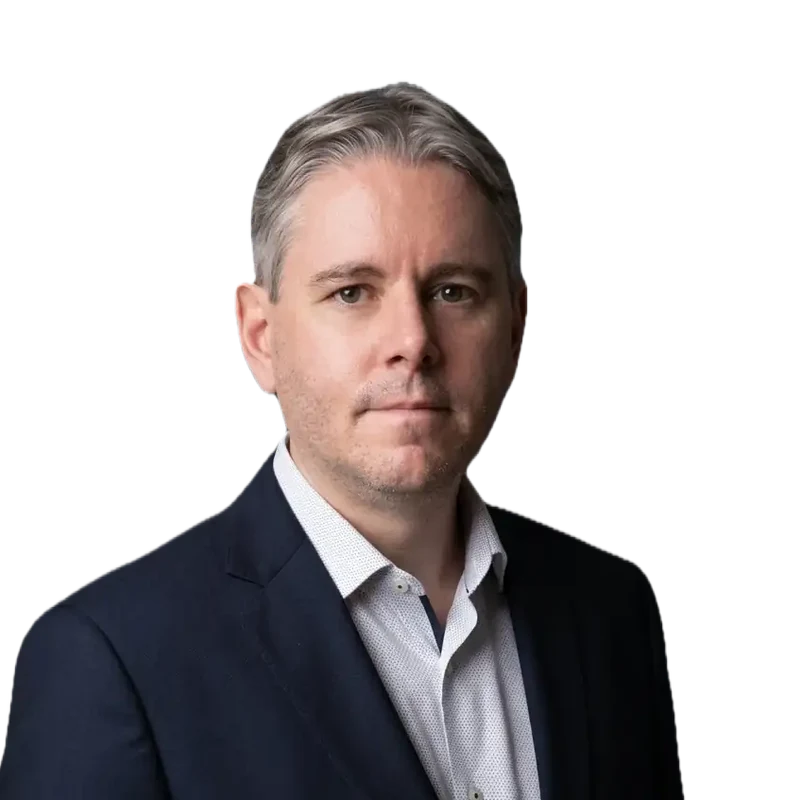
Benoît Meneau: CEO, CFO and Founding Partner

Your Plizz Contact

Benoît Meneau

CEO, CFO and Founding Partner

Corporate (re)structuring, cross-border transactions, international taxation, financial planning across SE Asia, MENA & Europe

20+ years

Why Plizz

Why choose Plizz for M&A advisory

Plizz is the Thai member firm of DFK International, a global network of accounting and advisory firms in 85+ countries. It was founded in 2015 by two operating CFOs who have structured and closed transactions in Thailand themselves.

DFK

International network
85+ countries

IR Global

Narai Partners, legal
cross-border reach

Benoît
Meneau

CEO / CFO
Founding Partner

Jérôme
Le Louer

Co-Founding Partner
& CFO

Founded by operating CFOs: Benoît Meneau and Jérôme Le Louer

Benoît Meneau (CEO, CFO, and Founding Partner) held CFO roles at listed and private companies across Southeast Asia, South Asia, the Middle East, and Africa, and has structured and closed transactions in Thailand. Jérôme Le Louer (Co-Founding Partner and CFO) brings the same operating background. Our advice comes from people who have sat in the CFO seat during a deal, not observed it from outside.

Fees sized for mid-market M&A

Transaction-services work for deals in the THB 50M–1B range at a fraction of typical Big 4 fees. You get a written quote for the retainer and success fee before the engagement starts. Walking away after due diligence is a normal outcome, and the fee structure reflects that.

DFK International cross-border network

Financial and tax due diligence coordinated with DFK member firms in 85+ countries, with one team accountable for targets outside Thailand and for buyers with foreign shareholders. Cross-border legal work is coordinated through Narai Partners (an IR Global member).

Financial and tax due diligence from one firm

Financial and tax issues are linked. Revenue recognition errors create CIT exposures, and related-party flows raise both transfer pricing and Section 65 Ter questions. Splitting the work between firms adds cost and leaves gaps. Plizz delivers both in one working file.

Common Questions

Frequently Asked Questions

Answers to the most common questions before and during engagement.

Insights

Guides on this topic

See all insights

Get Started

Get a quote in 1 business day

Tell us the deal size, structure, and timeline, and whether you are buying or selling. A senior partner reviews it and quotes the engagement before you commit. No retainer is due until the scope is agreed.

Get a quote

No commitment · Reply within 1 business day